
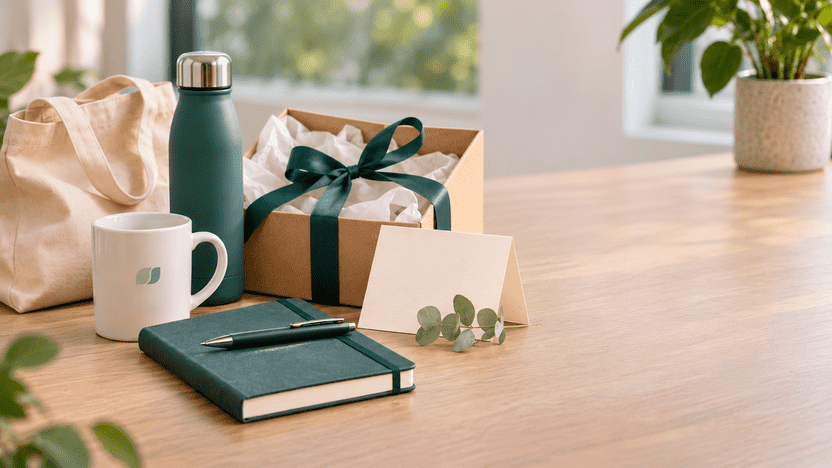
Explained
Are Corporate Gifts Tax Deductible in the Netherlands in 2026?
5 min read · Updated November 2026 · By Loopper
Yes, corporate gifts can be deducted as business expenses in the Netherlands. Branded pens, mugs and bags are not included in the Dutch Tax Administration's list of expenses subject to limited deductibility. Different rules apply to gifts of food, drinks and other consumables: in 2026, the first €5,700 of relevant expenses is not deductible under the threshold method, or qualifying income-tax businesses can opt for an 80% deduction. You can generally reclaim VAT provided you spend no more than €227 excluding VAT per recipient per financial year.
Key points
- VAT: generally recoverable up to €227 excluding VAT per recipient per financial year.
- Food, drinks and other consumables: subject to limited deductibility (the €5,700 threshold or an 80% deduction; 73.5% for companies subject to Dutch corporation tax).
- Branded practical gifts: not included in the list of expenses subject to limited deductibility.
- Gifts for employees: covered by the Dutch work-related costs scheme (WKR), with a 2% tax-free allowance on the first €400,000 of payroll.
01 · WHAT QUALIFIES
What counts as a corporate gift?
In this article, a corporate gift means a present given to an existing customer, supplier or business partner without expecting anything in return. Examples include a Christmas gift, a thank-you gift after a project or a small present to mark an anniversary. Giving away items to people who are not yet customers, for example at a trade show? Ask your accountant how to record those costs. You can also explore our trade show giveaways.
Gifts for your own employees are treated differently under Dutch tax rules. They fall under the work-related costs scheme (WKR), explained below.
02 · BUSINESS EXPENSES
How much can you deduct from your taxable profit?
It depends on what you give. The Dutch Tax Administration identifies gifts of food, drinks and other consumables as subject to restricted deductibility. These costs are grouped with other business entertainment expenses, such as business lunches and conferences.
| Type of gift | Examples | Deduction from taxable profit in 2026 |
|---|---|---|
| Practical gift with a logo | branded pens, printed mugs, cotton bags | Ordinary business expenses |
| Food, drinks and other consumables | wine as a corporate gift, coffee with a personalised label | Sole traders and general partnerships: the first €5,700 is not deductible under the threshold method, or deduct 80% instead. Private and public limited companies (bv and nv): deduct 73.5%, or apply the threshold method. |
Example: a branded mug or a Christmas hamper?
You give Christmas gifts to 100 customers. You operate as a sole trader and have no other business entertainment expenses.
| Branded mug + pen | Hamper with wine and treats | |
|---|---|---|
| Cost per customer (excl. VAT) | €7.50 | €60 |
| Total cost | €750 | €6,000 |
| Deductible from taxable profit | €750 (in full) | €4,800 (80%), or €300 using the threshold method |
| Can you reclaim VAT? | Yes, below €227 per customer | Yes, below €227 per customer |
A practical gift with your logo may therefore be more tax-efficient. It also keeps your brand visible in everyday use. For budget-friendly ideas, browse our affordable corporate gifts and corporate gifts under €2.
03 · VAT
When can you reclaim VAT on corporate gifts?
Under the Dutch rules covered here, you can generally deduct input VAT if you spend no more than €227 excluding VAT per recipient per financial year. If you exceed that amount, the VAT on gifts to that recipient is generally not deductible, and you may need to repay VAT you previously reclaimed.
- Exception: if the recipient could have purchased the gift for business purposes and deducted at least 30% of its VAT, you may also be allowed to deduct VAT above the €227 limit.
- Per person or per company? The Dutch Tax Administration refers to each recipient, while the Netherlands Chamber of Commerce (KVK) refers to each company. If in doubt, add together all gifts given to the same company.
- All gifts count: a Christmas present, a thank-you gift in June and an anniversary gift are considered together against the same €227 limit.
Example. In December, you send one customer a Christmas gift worth €150, having already sent them a €100 gift in June. Both prices exclude VAT. The combined amount is €250, exceeding the threshold. The VAT on both gifts is therefore not deductible under the general rule.
04 · EMPLOYEES
What about gifts for your employees?
Christmas hampers and welcome gifts for staff fall under the Dutch work-related costs scheme (werkkostenregeling, or WKR). In 2026, employers can spend 2% of the first €400,000 of their taxable payroll free of additional tax, plus 1.18% of the amount above that. Amounts exceeding this allowance are subject to an 80% final levy payable by the employer. You can also read our article about welcome packs for new employees.
05 · PRACTICAL TIPS
How can you choose corporate gifts tax-efficiently?
- Choose practical branded products. These do not fall under the specific restriction for food, drinks and other consumables. For inspiration, explore our sustainable corporate gifts.
- Keep a record for each customer. That makes it easier to check whether you remain below the €227 VAT threshold.
- Record food and drink costs separately. At year-end, you can compare the threshold method with the 80% deduction if it applies to your business.
- Order in good time. A digital proof lets you preview how your logo will appear. Learn about suitable techniques in our guide to printing options or explore the complete knowledge base.
This article provides general information about Dutch tax rules, based on guidance from the Dutch Tax Administration (Belastingdienst) and the Netherlands Chamber of Commerce (KVK), as of November 2026. It does not constitute tax advice. Discuss your circumstances with a qualified accountant or tax adviser.
Looking for the right corporate gift? Browse our range and request a free digital proof. Explore personalised corporate gifts
Further reading

What do our clients say?
 Free design & unlimited revisions
Within 1 hour!
We pride ourselves in a fast but qualitive service without exception. Within 1 hour of your offer request or order, we will provide you with a free digital mock-up without any strings attached. This way we make sure to have a good start to making that deadline!
 Custom solutions for every budget
Create your own product!
We go above and beyond to make sure you are happy. We offer over 6000 products that you can make your own. Looking for that special product? We have our own creative department that custom designs your idea. You name it, we produce it!
 Trusted by 10,000+ companies for 24 years
With 24 years of experience we have learned that human contact and knowledge about our products is key to what we do. We distinguish ourselves by always making sure that there is someone allocated to your project that will think along with you to get the best results.
About Edwin den Hartog - Founder of Loopper
Edwin den Hartog is the founder of Loopper and a hands-on expert in promotional merchandise with over 20 years of industry experience.
From helping major European brands to leading one of the fastest-growing promo companies in Europe.
Edwin’s mission is simple: to deliver creative, high-quality products backed by personal service and fast turnaround.